Insight note · 18 November 2026
Epiroc’s close order-growth rates follow different paths
Anvilmore Research Team
Epiroc’s equipment orders grew 16% organically year on year in Q3 2026; Service orders grew 13%. For suppliers assessing demand around mining equipment and its support needs, the closeness needs context. Across this global mining-and-infrastructure supplier’s recent history, those two rates arrived by different paths.
The latest report, released on 28 October and current as checked on 17 November, covers the quarter ending 30 September. Its eleven comparable quarterly observations show Service growth positive throughout, with smaller movements than equipment growth. Service’s latest rate is also its highest in that window: the support stream has continued to change during the equipment recovery.
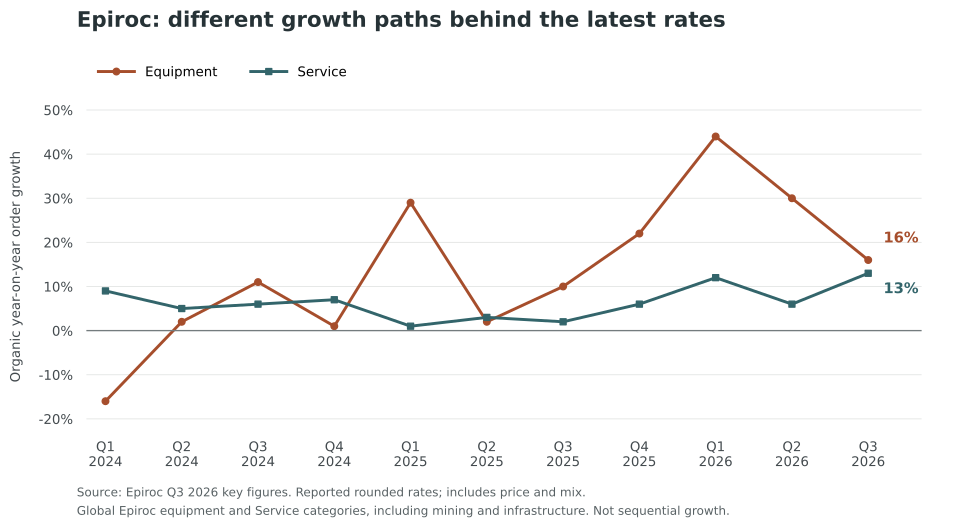
Source: Epiroc quarterly key figures. Reported rounded organic year-on-year rates for global Equipment and Service orders; each quarter compares with the same quarter a year earlier.
Equipment growth began at −16% in Q1 2024. It reached 29% a year later, fell to 2% in Q2 2025, then rose to 44% in Q1 2026 before easing to 30% and 16%. Service remained between 1% and 13% across all eleven quarters. Its 2026 path was 12%, 6%, then 13%: sustained positive growth has included acceleration and setbacks in the annual rate.
Calculating across the full window gives a 60-percentage-point span for equipment growth, against 12 for Service. The median absolute movement between successive quarterly year-on-year rates is 14 points for equipment and 4 for Service. These figures describe the size of changes in annual growth rates; they do not measure sequential changes in order values or predict future variability.
The categories also matter commercially. Epiroc’s Service includes upgrades and digital solutions, extending beyond routine maintenance; it is not a measure of all aftermarket demand. Epiroc attributes Q3 Service strength partly to mid-life upgrades and digital automation and safety demand. Large orders and annual comparison bases affect equipment growth. Organic growth excludes currency and structural contributions but still includes price and mix, so it cannot be read as physical-volume growth.
The comparison starts in 2024 because electrification infrastructure moved from Service to Equipment then; the 2023 growth-rate tables were not restated. It provides a recent company-specific reference, rather than a complete economic cycle or a benchmark for all mining.
For supplier commercial leads interpreting current equipment-related and support-related enquiries, the measured distinction is the history behind the latest close rates: equipment growth has eased from a much larger rebound, while Service has reached its window high after eleven positive quarters. That is the present Epiroc demand reading; it does not establish an independent supplier’s future revenue stability.
Sources
- Epiroc Q3 2026 key figures: quarterly order-growth series, category notes and definitions.
- Epiroc Q3 2026 interim report, pp. 4 and 9: current orders and the Equipment & Service discussion.
- Epiroc financial publications: latest-report status checked 17 November 2026.
- Epiroc Capital Markets Day 2026 presentation: Service scope, upgrades and digital solutions.